· ReadyStack
Worked example
Real numbers from this tool, line by line.
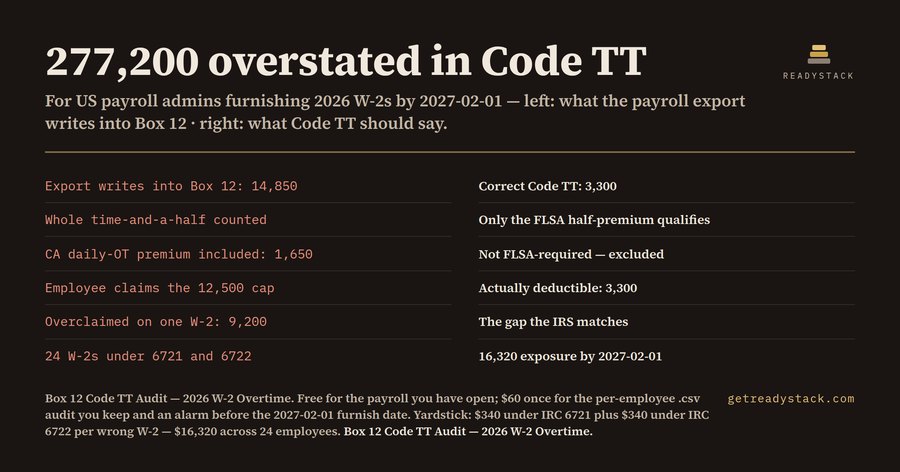
$277,200 overstated in Box 12 Code TT — US payroll administrators, a California restaurant group, 24 non-exempt staff, tax year 2026.
| Result | Figure |
|---|---|
| Correct Box 12 Code TT per employee | $3,300 |
| What the payroll export writes | $14,850 |
| Overstated per W-2 | $11,550 |
| Overstated across 24 W-2s | $277,200 |
| State-only daily premium excluded | $1,650 |
| Deduction allowed (single, $96,000 MAGI) | $3,300 |
| Deduction overclaimed from the wrong W-2 | $9,200 |
| IRC 6721 + 6722 exposure, top 2026 tier | $16,320 |
Inputs: a $22 regular rate, six hours over forty in the workweek, three daily-overtime hours California requires, fifty paid weeks, twenty-four employees.
2026 is the first year Form W-2 carries Box 12 Code TT. The IRS finalized the 2026 form and its instructions in January 2026, and Code TT is mandatory: every employer paying FLSA-required overtime to non-exempt employees must separately track and report qualified overtime compensation. The forms are furnished and filed by 2027-02-01: January 31, 2027 is a Sunday.
The trap is what qualified means. Under IRC 225 the deduction reaches only the overtime premium the FLSA requires: the one-half portion of time-and-a-half. On a $22 regular rate an overtime hour pays $33, and only $11 of it is qualified overtime compensation. The other $22 is straight time.
Follow the hours. Nine overtime hours a week are paid: six over forty in the week, three required by California after eight in a day. Over fifty weeks that is 300 FLSA hours and 150 state hours. Code TT should carry the $11 premium on the 300 FLSA hours, which is $3,300. The export writes the full $33 on all 450 paid overtime hours, which is $14,850. The gap is $11,550 on each W-2 and $277,200 across twenty-four W-2s.
California, Alaska, Nevada and Colorado are where the second layer bites: they require premium pay for hours over eight in a day even when the employee never crosses forty in the week. That premium is state law, not the FLSA, so it is not qualified overtime compensation. The three daily hours a week carry $1,650 of premium per employee that has to come out of the Code TT figure — and no export separates them: for wage-and-hour purposes they sit in the same earnings bucket.
The employee pays for the error. The 2026 deduction is capped at $12,500 ($25,000 joint) and reduced by $100 for each full $1,000 of modified adjusted gross income above $150,000 ($300,000 joint). Filing single at $96,000 of MAGI, the employee may deduct $3,300. Reading the inflated W-2, they claim the $12,500 cap — $9,200 more than the law allows, on a form the IRS matches line for line.
The employer pays twice for the same piece of paper: a wrong information return under IRC 6721, and the same wrong statement furnished under IRC 6722. For returns required to be filed in 2026 the tiers are $60 within thirty days, $130 by August 1, and $340 after that. Twenty-four wrong W-2s at the top tier, counted under both sections, is $16,320.
Other shapes land differently: six machinists at $38 with ten overtime hours a week overstate $118,560, with a real deduction of $8,080 at $168,500 of MAGI; forty nurses at $31 with four overtime hours and a joint return at $318,000 overstate $257,920.
A general overtime calculator totals gross overtime pay — the number that must not appear in Box 12 — and a chatbot hands back the full time-and-a-half. The FLSA-versus-state split, the cap, the phaseout and the doubled penalty are four rules applied in order.
The extension is a popup and a web page running the same engine: the correct Code TT figure, what the export writes instead, the overstatement per W-2 and across the payroll, the deduction after phaseout, and the 6721 plus 6722 exposure. Every calculation is free and unlimited. The $60 key does a different job: it exports the per-employee audit as a .csv you keep in the payroll file, and sets a browser alarm before 2027-02-01.
Questions people ask
What does this extension actually do?
It takes your regular rate, the hours over 40 in a workweek, and any state-only daily overtime hours, and returns the figure that belongs in 2026 Form W-2 Box 12 Code TT: the one-half FLSA premium. It then shows what a payroll export writes there instead, the dollar gap per W-2, and the IRC 6721 and 6722 penalty exposure on that gap.
Who is this for?
US payroll administrators, bookkeepers and controllers who run weekly payroll for non-exempt hourly staff — restaurant groups, manufacturing plants, clinics, contractors. It matters most in California, Alaska, Nevada and Colorado, where daily overtime is paid but is not FLSA-required, so it does not belong in Code TT.
Why not just ask a chatbot or use a free overtime calculator?
Free overtime calculators total gross overtime pay, which is the number you must not report. Chatbots answer with the full time-and-a-half and rarely separate state daily overtime from FLSA overtime. Neither applies the $12,500 cap, the $100-per-$1,000 phaseout above $150,000, or the doubled 6721 plus 6722 penalty on the same wrong form.
What is free and what does the $60 key add?
Every calculation is free and unlimited, in the popup and on the web page: correct Code TT, overstatement, deduction after phaseout, penalty exposure. The $60 key adds a different thing, not more of the same — a .csv export of the per-employee audit you keep in the payroll file, and a browser alarm before the 2027-02-01 furnish date.
What would this cost me if I got it wrong?
For returns required to be filed in 2026 the top-tier penalty is $340 per information return under IRC 6721, and a separate $340 per payee statement under IRC 6722. A 24-employee payroll with the wrong Box 12 figure on every W-2 carries $16,320 of exposure, against $60 once for the key.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.